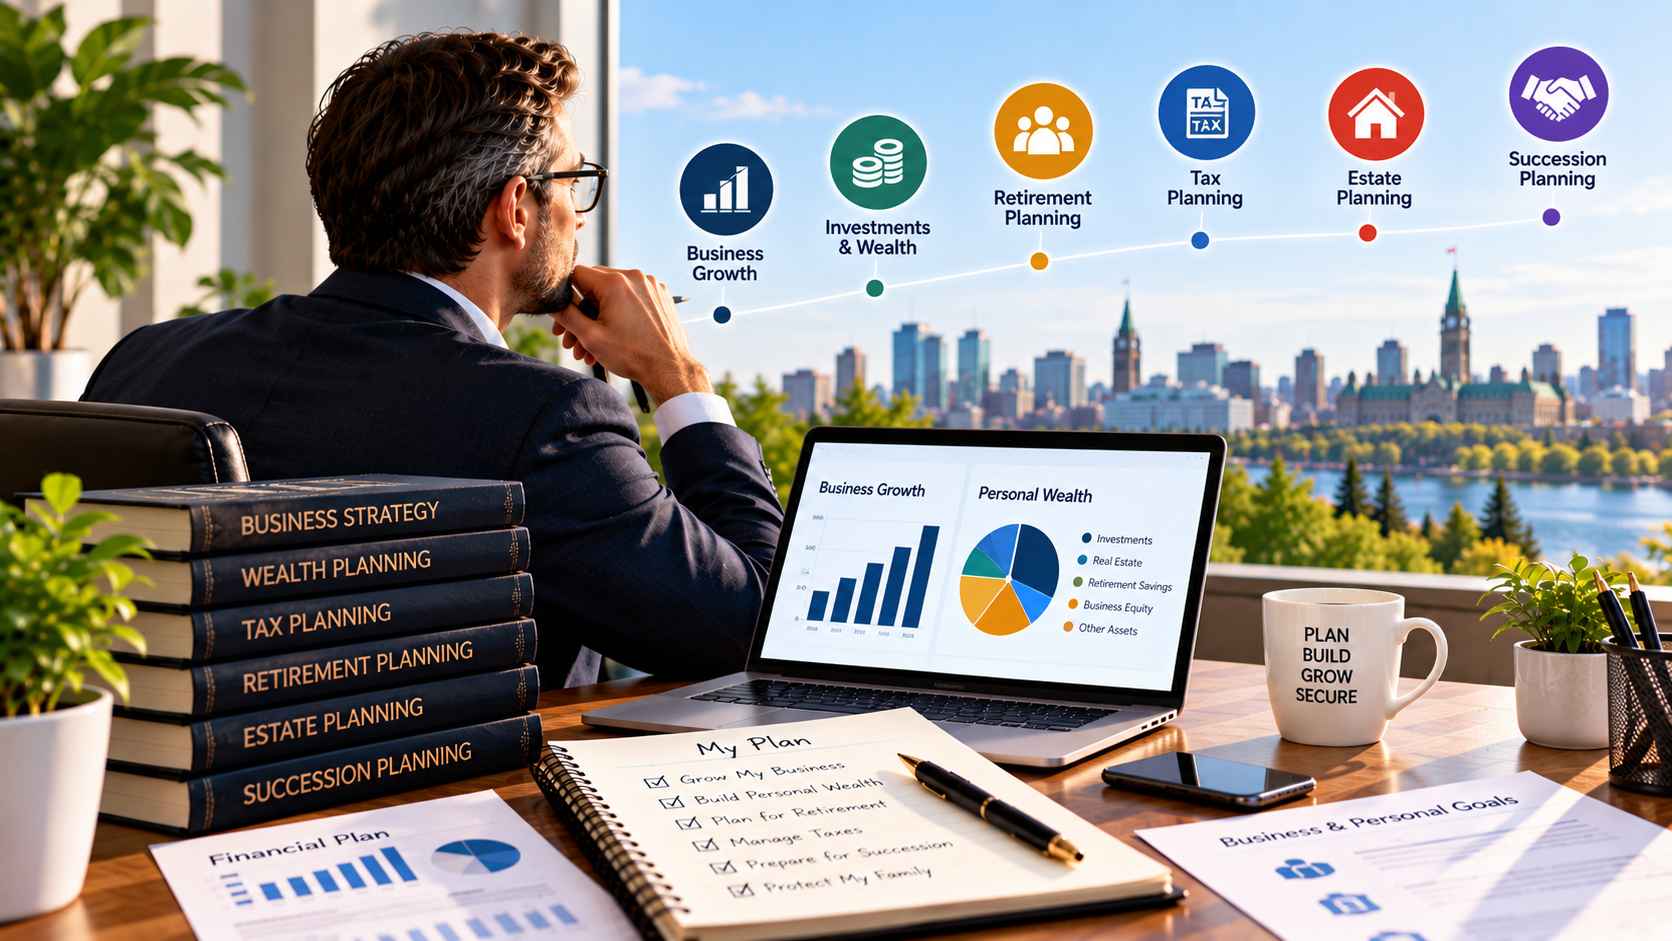
Running a successful business can make it easy to focus almost entirely on the company. Revenue, employees, customers, expansion, and cash flow demand attention every day. Personal financial planning can sometimes become a secondary concern.
For many entrepreneurs, however, the business is also one of their largest personal assets. That creates an important connection between business strategy and personal financial security.
A decision to reinvest profits, acquire another company, sell a business, or step away from day-to-day management can affect far more than the company’s balance sheet. It can influence retirement plans, personal investments, family goals, taxes, and future lifestyle choices.
Connecting business planning with personal wealth planning can help owners understand those relationships before a major transition arrives.
Business Growth and Personal Wealth
Business growth and personal wealth are related, but they are not necessarily the same thing.
A company can generate strong revenue while the owner continues to have most of their personal wealth tied to the business. That concentration may make sense during certain stages of growth, particularly when reinvesting capital is important to expansion.
Over time, though, an owner may want to build financial resources outside the company as well.
This could include personal investments, retirement savings, real estate, or other assets appropriate to the owner’s circumstances. The objective is not necessarily to reduce investment in the business. Rather, it is to recognize that personal financial security and business value serve different purposes.
Exponent Investment Management works in wealth management and financial planning, providing an example of how business ownership can be considered alongside broader personal financial objectives.
The connection becomes particularly important when an owner begins thinking about eventually reducing their involvement in the business.
Know Where Your Wealth Is Concentrated
A business owner may look at the estimated value of their company and feel financially secure. But business value and accessible personal wealth are not interchangeable.
A company’s value may depend on its future performance, industry conditions, customers, management team, and eventual transaction. Until an ownership transition actually occurs, the value remains tied to the business.
That makes it useful to understand how much of an owner’s overall financial position is concentrated in the company.
An owner might have substantial business equity but relatively limited investments outside the business. Another might have already built a diversified portfolio and therefore have a different level of dependence on a future business sale.
Understanding this distinction can help inform decisions about savings, investments, insurance, retirement preparation, and future business strategy.
It can also make conversations about succession more productive. Instead of asking only, “What is my business worth?”, an owner can also ask, “What will my personal financial position look like if I am no longer actively involved in the business?”
Build Personal Assets Alongside the Business
One way to reduce dependence on a future business outcome is to gradually build personal financial resources alongside the company.
For some owners, this may mean maintaining retirement savings or investments outside the business. For others, it may involve establishing appropriate cash reserves or considering other assets as part of a broader financial strategy.
The right approach depends on individual circumstances, including income, business structure, financial obligations, risk tolerance, and long-term goals.
Diversification can also be considered at the household level. If most of an owner’s wealth is represented by one private company, the overall financial picture may be quite different from that of someone whose wealth is spread across several types of assets.
The purpose is not to eliminate every form of risk. Business ownership itself can remain an important source of wealth and opportunity. The broader goal is to ensure that personal financial planning continues alongside business growth.
Plan for Retirement and Succession
Retirement can be particularly complicated for entrepreneurs because leaving the workforce may also mean changing ownership of the company.
Some owners plan to sell their business. Others may transfer it to family members, bring in partners, sell to employees, or retain ownership while stepping back from daily management.
Each option can affect personal income and long-term financial security differently.
Retirement planning therefore needs to consider more than a target retirement age. An owner may need to think about expected spending, investment assets, business income, potential sale proceeds, and other sources of retirement income.
The Government of Canada provides retirement-planning resources that encourage individuals to consider lifestyle, expenses, retirement timing, and multiple sources of retirement income when preparing for the future.
Succession planning deserves similar attention. The Government of Canada describes business succession planning as important for helping Canadian entrepreneurs prepare for ownership transitions, including selling or transferring a business. Business succession planning guidance
Starting these conversations early can provide more flexibility than waiting until an owner is ready to leave.
Think About Taxes and Estate Planning
Business and personal wealth can become closely connected when considering taxes and estate planning.
A business sale, ownership transfer, retirement income, investment transactions, and estate transfers may each have different tax considerations. The appropriate treatment can depend on the business structure, assets involved, transaction details, and individual circumstances.
For that reason, tax planning should not necessarily be left until the year of a major transaction.
Estate planning is also important for owners who have accumulated significant business and personal assets. Family members may have different expectations about the future of the company, while an owner’s personal wishes may extend beyond business ownership.
Wills, beneficiary arrangements, insurance, investment assets, property, and business interests may all need to be considered as part of the broader picture.
Financial planning does not replace legal or tax advice. Instead, it can help identify where financial, tax, and estate decisions overlap so that the appropriate professionals can coordinate their work.
Review the Plan as the Business Evolves
A business owner’s financial plan should evolve as the company and personal circumstances change.
A rapidly expanding company may require substantial reinvestment. Later, the owner may shift toward building personal investments. A major acquisition could change the owner’s exposure to business risk. A new family responsibility could change financial priorities. A potential buyer could create an unexpected opportunity to transition ownership.
These developments can affect both business strategy and personal financial objectives.
Regular reviews can help owners reassess questions such as:
- How much personal wealth remains tied to the business?
- Are retirement goals still realistic under different scenarios?
- Is there enough liquidity outside the company?
- Has the intended succession path changed?
- Do estate and family objectives still reflect current wishes?
- Have changes in income or business structure created new planning considerations?
The purpose is not to react to every short-term change. It is to make sure the broader strategy continues to reflect the owner’s current position and future priorities.
Bringing Business and Personal Planning Together
Entrepreneurs spend years building companies, but eventually many will face a decision about how much longer they want to remain actively involved.
That transition can be easier to navigate when personal financial planning has developed alongside the business rather than being postponed until the end.
financial planning for business owners can provide a framework for connecting business ownership with personal investments, retirement objectives, succession considerations, and longer-term wealth goals.
A business can remain the centre of an entrepreneur’s financial life while it is growing. But personal financial security does not have to depend entirely on what happens to the company.
By considering business value, personal assets, retirement, taxes, estate planning, and succession as connected parts of the same financial picture, owners can make decisions with a clearer understanding of how today’s business choices may affect tomorrow’s options.
The result is not a guarantee about what the future will bring. It is a more organized way to prepare for the possibility that the business will eventually change, grow, transfer ownership, or become part of the next chapter of the owner’s life.